There’s a peculiar Indian ritual that happens every March.
Millions of salaried people sit down with Form 16, a cup of chai gone cold, and the creeping realization that despite a raise, a bonus, and a LinkedIn post about “growth,” their actual bank balance looks suspiciously similar to last year’s.
Somewhere between the payslip and the passbook, a chunk of their money quietly vanished — not stolen, not lost, just taxed.
Efficiently. Legally. Repeatedly.
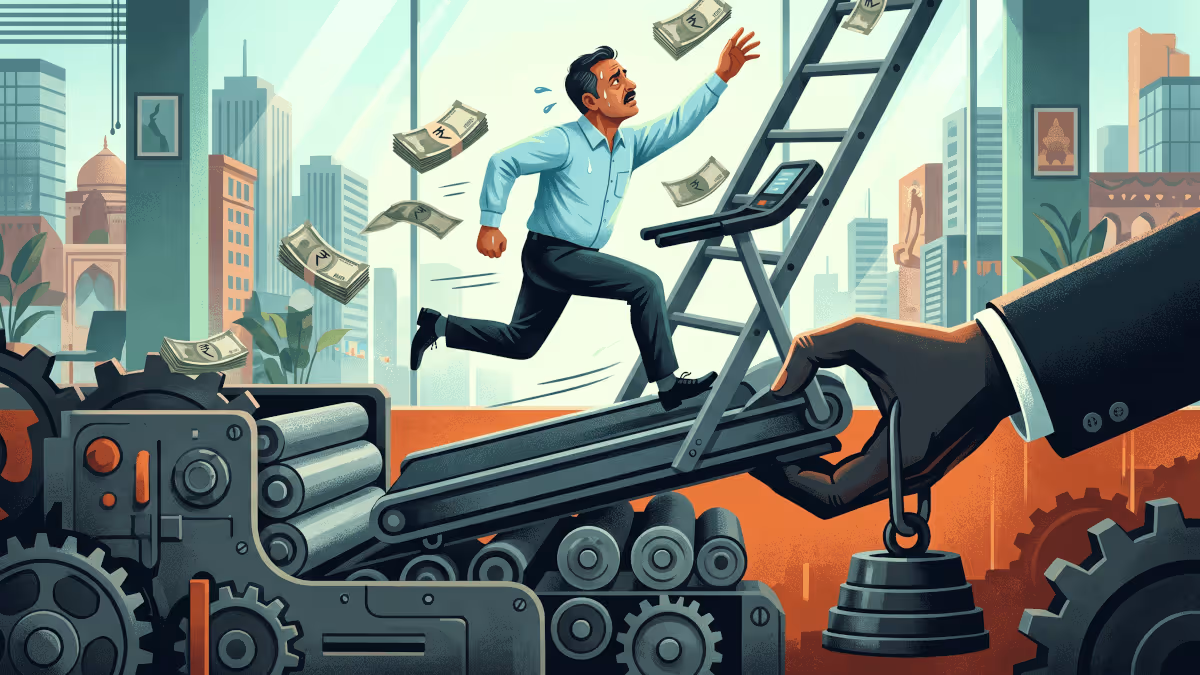
This isn’t a conspiracy theory. It’s arithmetic. And it’s worth asking, in a spirit of humour rather than outrage: is the Indian tax system actually designed, structurally, to keep the middle class treading water while everyone else finds a side door?
Let’s open the ledger.
Act 1: The salaried are sitting ducks.
If you earn a salary in India, your employer deducts tax at source before the money even says hello to your bank account. You don’t get a vote. You don’t get a “wait, let me consult my CA first.” TDS arrives like an uninvited relative — early, uncompromising, and impossible to argue with.
Compare this to a business owner or a self-employed professional, who can offset a genuinely impressive buffet of expenses against income: office rent, travel, that “client dinner” which was suspiciously at a five-star hotel, depreciation on the car, the laptop, the phone, even parts of the home if it doubles as an office.
The salaried employee, meanwhile, gets a standard deduction that a chartered accountant could compute on a coffee-stained napkin, and precious little else. Your commute doesn’t count. Your work-from-home electricity bill doesn’t count. Your “I bought a better chair so my back doesn’t give up on me” doesn’t count.
It’s the tax equivalent of one team playing with a bat and the other playing with a bat, a helmet, pads, and a personal statistician.
Act 2: GST, the tax that doesn’t care how much you earn.
Income tax at least pretends to be progressive — the more you earn, the more you (theoretically) pay. GST has no such pretensions. Whether you’re a crorepati or someone counting coins for milk, you pay the same 18% on that bottle of shampoo.
A tax that takes a larger percentage of income from low-income earners than from high-income earners because it is applied uniformly to everyone. This is what economists politely call a “regressive tax”: it takes a proportionally bigger bite out of smaller incomes.
The middle class, unlike the ultra-wealthy, spends most of what it earns — on rent, school fees, insurance, the occasional Swiggy indulgence, and yes, shampoo.
Every one of those transactions gets a GST toll booth.
The wealthy, who save and invest a larger share of their income, simply encounter fewer toll booths per rupee earned. It’s not villainy; it’s just how consumption taxes behave everywhere. But it does mean the middle class ends up paying tax coming and going — once when the salary lands, and again every time it leaves.
Act 3: Cess, surcharge, and other words designed to sound harmless.
Somewhere in the Income Tax Act live two quiet little riders called “cess” and “surcharge”; they sound like minor characters in a Bollywood ensemble cast, but they’re not decorative.
A 4% health and education cess sits on top of your calculated tax, no matter which slab you’re in. Surcharges stack on higher incomes, sometimes pushing the effective tax rate well past the headline number people quote at dinner parties.
The genius of a cess is that it never shows up in the slab table everyone shares as a WhatsApp forward. You think you’re paying 20%. You’re paying 20% plus a garnish of 4% on top of that 20%. It’s the tax version of a restaurant bill that says “prices exclusive of taxes and service charge” in 6-point font.
Act 4: Capital gains — where money can finally relax.
Now here’s where it gets genuinely interesting.
If you earn money through labour — showing up, doing the work, answering emails at 11 PM — it’s taxed as income, at your full slab rate. But if your money earns money for you, through long-term capital gains on equities, it gets a comparatively gentler ride.
Long-term gains on listed shares and equity mutual funds are taxed at a flat, relatively modest rate, regardless of your income bracket — a rate a salaried person in the top slab can only look at wistfully.
The uncomfortable joke here writes itself: in India, it is often cheaper, tax-wise, to own wealth than to earn it. The middle class, whose primary asset is usually a job and maybe a flat bought with a 20-year loan, doesn’t have enough surplus capital sitting in equities to make this advantage count for much.
The people who benefit most from favourable capital gains treatment are, definitionally, the people who already have capital.
It’s less a conspiracy against the middle class and more a party the middle class wasn’t quite invited to, mostly because it couldn’t afford the entry fee.
Act 5: The EMI trap and the disappearing deduction.
The Indian middle-class dream has a very specific shape: a flat, a car, a child’s education fund, and health insurance — all financed, naturally, through EMIs that quietly eat 40-50% of take-home pay for two decades. Under the newer, simplified tax regime — the one now offering relief up to ₹12 lakh — most of the old deductions for home loan interest, insurance premiums, and 80C investments have been stripped away in exchange for lower slab rates. That’s a genuinely fair trade for many people. But it also means the specific middle-class instruments of wealth-building — the SIP, the insurance policy, the home loan — no longer buy you the tax breaks they once did. You can have simplicity, or you can have incentives for saving. Increasingly, you’re asked to pick one.
Act 6: The plot twist nobody tells you.
Here’s where the satire needs a reality check, because comedy without facts is just complaining with better timing.
As of the 2025 Budget, income up to ₹12 lakh (₹12.75 lakh for salaried taxpayers, thanks to the standard deduction) attracts zero income tax under the new regime — a meaningful jump from the ₹7 lakh threshold that existed just two years earlier. Slabs above that were also softened. This is, by any honest measure, real relief for a large chunk of the middle class, not a token gesture. The government’s own framing is that this is meant to boost disposable income, consumption, and savings — and for many households, the math genuinely works out better than before.
It’s also worth remembering why this tax structure exists at all. Direct taxes on salaried, easily-traceable income fund roads, defence, subsidised food, healthcare schemes, and welfare programs that reach far more people than the taxpaying minority itself — India’s direct taxpayer base is still a relatively small slice of the population. GST, for all its regressive quirks, is also what allowed the country to fold dozens of separate state and central levies into one system, making it harder (in theory) to dodge tax entirely by shopping around state lines. None of this is villainous; it’s the ordinary machinery of a country trying to fund itself while its tax base is still maturing.
So, is the system “designed” to keep the middle-class and salaried-class “middle”?
Probably not designed in some boardroom sense, with a mustache-twirling policymaker rubbing his hands together. It’s more that the middle class is the most legible class to the taxman — salaries are recorded, TDS is automatic, PAN-linked transactions leave a trail, and there’s rarely an accountant creatively categorising a family vacation as a “business development expense.” Cash-heavy informal income and sophisticated capital income both have more room to manoeuvre, for very different reasons.
The middle class, caught in the middle (hence the name), ends up as the most reliable, trackable, and therefore heavily-tapped source of revenue.
It isn’t a plot. It’s a pattern. And patterns, unlike plots, can be changed — which is exactly what the last two Budgets have started nudging toward.
The closing argument.
If Indian taxation were a Bollywood movie, the middle class would be the reliable, hardworking character who never gets the flashy entrance but somehow ends up paying for the whole wedding. Not the villain’s story, not quite the hero’s either — just the one holding the family together while everyone else gets the better lighting.
The good news? The lighting is slowly improving. The ₹12 lakh threshold, simplified slabs, and periodic relief measures suggest policymakers know exactly who’s been footing the bill. The bad news? Until deductions catch up with how the middle class actually builds wealth — home loans, insurance, long-term savings — “financial freedom” will keep arriving a few rupees short of the finish line.
Until then, keep your Form 16 handy, your jokes handier, and maybe — just maybe — start reading the fine print on that “cess.”

Leave a Reply